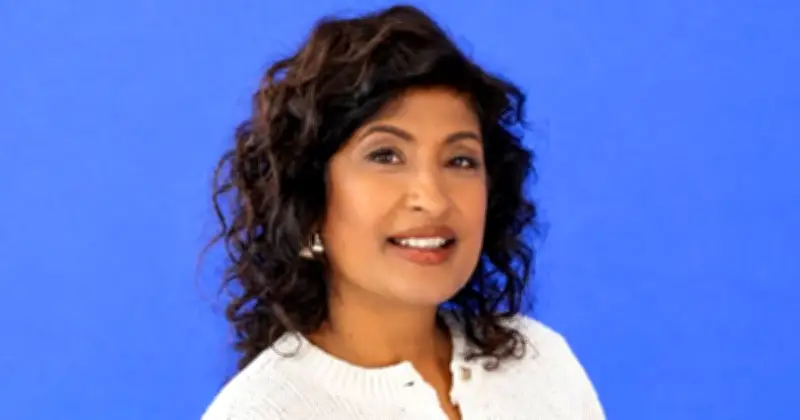
Fighting over possessions while overlooking a valuable pension is among the costly mistakes couples make when getting divorced, according to a financial adviser.
Rakhee Wood, founder and Independent Financial Adviser at Butterfly Financial Planning, said the stress and emotion of a marriage ending could cause people to focus on the wrong financial decisions.
Personal experience shapes advice
Rakhee's interest in divorce planning is personal. When she returned home from university aged 21, her parents were beginning a divorce that would take four years to resolve.
Her father had been the breadwinner, while her mother was responsible for the home and their three children. Rakhee became her mother's "right-hand woman", helping her understand legal correspondence, proposed settlements and what she would need to support herself.
Rakhee said: "The raw anxiety of that situation really stayed with me. My mum didn't understand what was happening, how much she was going to get or whether she was going to be okay."
Biggest financial mistakes made during divorce
One of the biggest mistakes Rakhee now sees is concentrating on keeping the family home without properly considering pensions and other assets. Someone may feel secure because they will receive a mortgage-free property, but a house does not automatically provide the income needed to pay monthly bills or fund retirement.
Rakhee said: "A lot of people think about the present: 'As long as I've got the roof over my head, I'll let the pension go.' I still see people saying they have excluded the pensions because their former partner has given them something else. Make sure you are totally comfortable with that, because sometimes it is not fair."
Another mistake is allowing emotion to drive costly arguments over relatively inexpensive possessions. Rakhee recalled cases in which people had paid solicitors to dispute items such as paintings while potentially overlooking assets worth considerably more. She calls the value of avoiding unnecessary conflict the "peace premium".
Rakhee said: "It's all very well having a Rottweiler in your back pocket, a solicitor helping you fight for every single thing, but their costs are adding up. On one hand, someone has let the pension go, but then they are arguing over a Buddha painting. That is totally the wrong way around. Sometimes it may be better to let things go for your peace, your sanity and your ability to move on."
Look at the long term
Divorcees should also examine what a settlement will mean several years later, rather than only checking whether it meets their immediate needs. For example, maintenance payments may end after a set period, potentially leaving someone unable to afford the family home. Cash-flow planning can help establish whether they will need to downsize and how much money must be retained for retirement.
Rakhee recommended dividing an overwhelming list of jobs into three categories: what needs to happen now, what should happen soon and what can wait until later.
Review wills as well
People should also review their will, pension beneficiary nominations and any life insurance placed in trust. Otherwise, an outdated nomination could create confusion or result in money being directed contrary to their wishes.
Rakhee added: "Understand the numbers and what your plan will look like as a single person. Focus on the bigger picture, try to keep things amicable where possible and get independent legal and financial advice before agreeing to anything.
"The objective is not simply to finish the divorce. It is to make sure the settlement allows you to begin the next chapter with confidence."