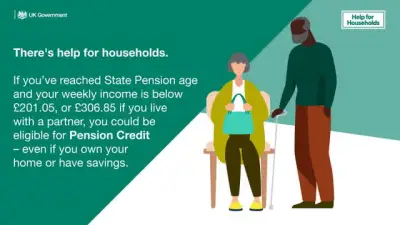
Older state pensioners across the UK are on course for a £373.40 annual payment boost from next April under Andy Burnham’s Government. State Pension rates are uprated at the start of every new tax year on April 6 in line with the triple lock.
This is a UK Government guarantee that sets the new payment rates based on the highest out of three measures: the consumer price index (CPI) measure of inflation (measured for September the year before), average wage growth between May and July the previous year, or a minimum of 2.5%. Despite the Prime Minister announcing that he intends to end the triple lock in 2030, the current system of calculating State Pension increases will remain in place until then.
Triple Lock Rise Set for April 2027
Under this triple lock system, the State Pension is set to rise by 3.9% in April 2027 in line with average wage growth. The average earnings figure is the highest out of the three triple lock measures, as it was last year, so it is set to be used again to set the 2027/28 State Pension rates.
This 3.9% increase would take the old basic State Pension up from £184.90 per week to £192.10, a weekly rise of £7.20. As such, older pensioners entitled to the maximum amount would get an annual payment boost of £374.40 under the new rates.
Qualifying Years and New State Pension Impact
You’ll get the basic State Pension if you’re a man born before April 6, 1951, or woman born before April 6, 1953, but your payment amount depends on your National Insurance record. To get the full payment, a man born between 1945 and 1951 usually requires 30 qualifying National Insurance years, while men born before 1945 require 44 qualifying years. For women, you’ll need 30 qualifying years if you were born between 1950 and 1953, or 39 qualifying years if you were born before 1950.
As for younger pensioners who get the new State Pension, a 3.9% increase would give claimants an extra £9.40 per week if they get the full amount, with the weekly rate rising from £241.30 to £250.70. For those entitled to the maximum payment, this would provide an annual boost of £488.80 in the 2027 to 2028 tax year.
Ed Monk, Associate Director at Fidelity International, explained: “The State Pension in the current 2026/27 financial year is set at £241.30 a week, or £12,548 a year, for those claiming the full new State Pension. That follows a 4.8% rise from the year before based on the increase in wages, which was the highest of the three measures.
“And we now know the rise that will apply in the 2027-28 tax year. In April 2027 the State Pension will rise to £250.70 a week - £13,036.40 a year - following a 3.9% rise in wages that was confirmed in labour market data published this month.
“Consider that as recently as the 2022/23 tax year it was just £185.15 a week - meaning that by next year it will have risen by more than 35% in five years.”
Tax Implications and Future Changes
As the personal tax allowance has been frozen at £12,570 since 2021, it means state pensioners will be caught within the tax net for the first time. So far, the Government has said pensioners who are wholly dependent on the new State Pension – with no private pension – or the old basic State Pension, “with no increments”, will not have to pay tax.
It’s still unclear exactly how the policy will work, but the Government is expected to set out further details in the Budget on October 28. In his first Labour conference speech as party leader and Prime Minister, Mr Burnham said he will honour the manifesto promise to keep the triple lock unchanged throughout this Parliament, but from April 2030 this will be adjusted.
From this point, he has proposed that the State Pension will continue to rise every year at least by prices or 2.5% - removing the link to average earnings - with the savings generated from this change to be used to “build up our National Care Service”. Mr Burnham said the State Pension “will hold its value relative to earnings over time so that pensioners will always share in the rising prosperity of the nation”.