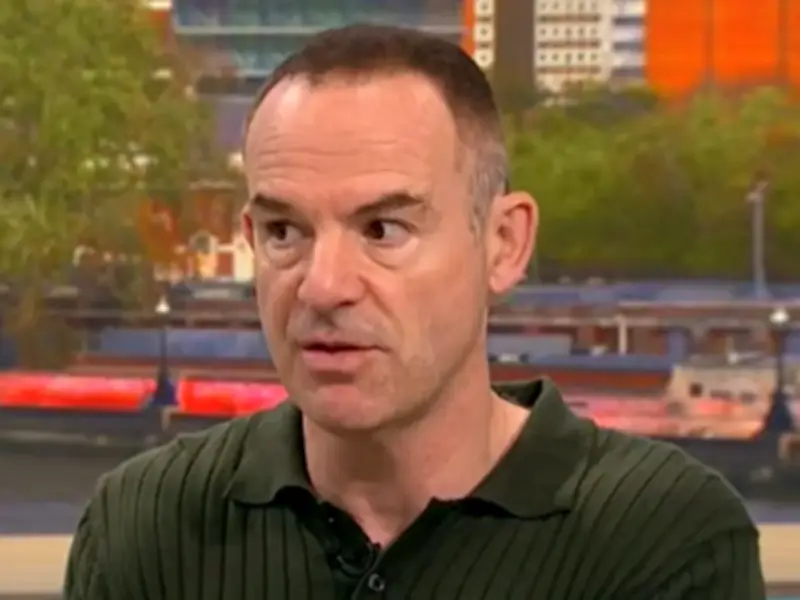
Martin Lewis has highlighted what he calls the "irony" of Premium Bonds, suggesting they are often given to the people they are "least suited" for. The money-saving expert discussed the popular savings tool on his BBC podcast, questioning whether it is the best home for Britons' money.
More than 24 million people hold over £136 billion in the government-backed scheme. Unlike standard savings accounts, Premium Bonds do not pay interest; instead, they offer tax-free prizes. The odds of winning stand at 21,000 to 1 for every £1 Bond held, with the annual prize fund rate at 4.35 per cent.
Who should avoid Premium Bonds?
Mr Lewis said: "Is it time to ditch premium bonds? It is the UK's most popular form of savings with over £136billion in them. Yet the irony of these bonds for me is that we tend to give them to the people that they are least suited for."
He explained that the prize fund rate "sounds good, but actually, most people with typical luck will win less than that. And you can earn more just in a standard, top, bog-standard easy-access savings." He also pointed out that while Premium Bonds are government-backed, the maximum investment is £50,000, whereas "all UK-regulated savings are protected up to £120,000 per person, per financial institution."
Who are they good for?
Mr Lewis said Premium Bonds are mainly suitable for "people with nearly the maximum, so the closer to winning that prize fund rate, and those who are already going to pay tax on other savings. They've used up their cash ISAs, they've used up their savings allowances, where the tax-free nature of the bonds comes into play."
He added that they are "not good for particularly" people who receive small amounts and do not pay tax, such as children, yet "we often give premium bonds to children."
NS&I, the government's state-owned savings bank, lists the advantages of Premium Bonds as a chance to win tax-free prizes from £25 to £1 million, easy access to money, and the ability to buy a savings gift for a child under 16. However, it notes they are not ideal for those seeking a regular income, guaranteed returns, or to save jointly with someone else.
Holders share their experiences
After Mr Lewis posted a video on Facebook, Premium Bond holders shared mixed reactions. One person said: "I keep it as my emergency fund, I know it's safe and I win most months with the maximum investment. It's the excitement of opening the app and seeing what I've won. It might be the jackpot one month!"
Another commented: "What Martin fails to mention when comparing to savings accounts is that Premium Bond winnings are tax free but interest on savings is not. And if you're a 40% taxpayer then you only get £500 tax free of savings interest or none if you're a 45% taxpayer." Others pointed out that ISAs offer tax-free savings options, as Mr Lewis noted.
One holder said: "I've got the maximum amount and only won £425 this tax year, I'm definitely having worse than average luck. Considering moving the money because I could get more interest in savings, even after tax!" Another added: "I like them, I have full allocation and have won something every month for the past 41 months. Prior to that the winning streak was 36 months, so just one barren month out of 78 months. I calculate it to average around 4.8%, tax free."