
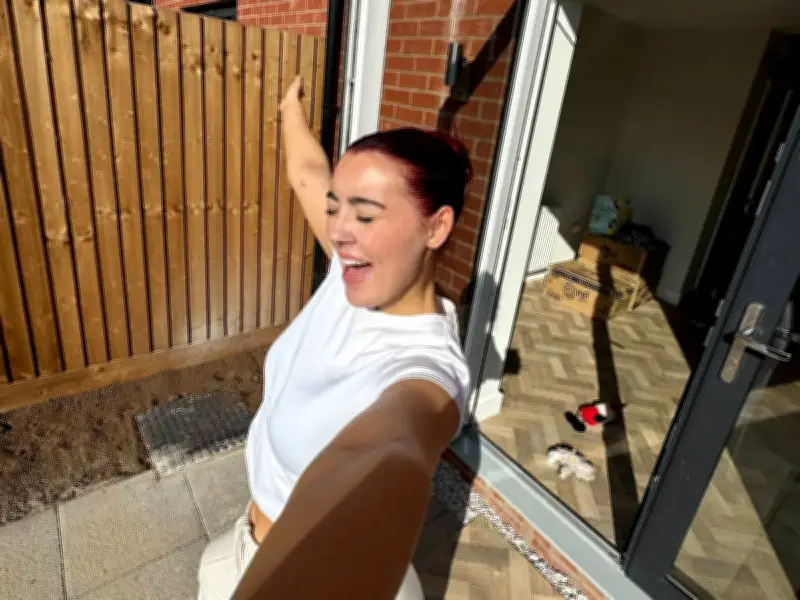
A 25-year-old first-time buyer secured her own home with just a 5 per cent deposit, after saving £12,000 and using a new-build incentive scheme. Cerys Gardiner, now 27, from Nottingham, Nottinghamshire, completed the purchase in August 2025, spending under £15,000 in total including solicitors' costs.
How the 5 per cent deposit scheme worked
Cerys had saved only £4,000 in her lifetime ISA and feared homeownership was still years away. After speaking with a mortgage adviser, she discovered she could buy a new-build property through a 5 per cent deposit scheme, arranged through Nationwide. Under the scheme, her developer contributed the remaining 5 per cent.
She found a three-bedroom property for less than £250,000 on a new development. To reach her deposit goal, she saved an extra £8,000 over six months through her role as a marketing manager and side work as a freelance marketer, taking on additional projects. Her monthly mortgage payment is £982, and with bills included totals £1,400, representing roughly 50 per cent of her take-home salary.
Saving from £4,000 to £12,000
Cerys reserved her home in March 2025 and had four months to gather the deposit. She said: "I kind of had two months to make sure I could max it out and the way I was able to do that was move home temporarily. The money I was paying in rent would go into that. I worked a hell of a lot of freelance jobs in five to six months to be able to bolster that."
She added: "I was able to make it happen and go from £4,000 to £12,000." Initially drawn to older properties with character, Cerys changed her mind after a mortgage adviser suggested a new build. She recalled: "He said actually you don't need to have thousands and asked if I had considered a new build. He said they can give incentives with a 5 per cent deposit and support."
Market context and mortgage details
According to Bank of England figures, the proportion of UK mortgages with deposits below 10 per cent of the property value is now at its highest level since 2008. The typical deposit for first-time buyers currently sits at approximately 20 per cent. Lenders including Lloyds, Santander, Skipton and Yorkshire Building Society have launched products covering upwards of 95 per cent of a property's value, with some reaching as high as 100 per cent. These products typically come with higher interest rates, aren't suitable for all property types or borrowers, and carry risks that customers need to understand.
Cerys took out a 40-year mortgage term with a 4.49 per cent fixed rate for five years. She said: "I picked 40 years as I was more focused on it being affordable now as realistically, I might remortgage at some point or move house. The 5 per cent deposit was completely condition free and the developers offered that as incentive for people to buy. People think it's shared ownership but it's absolutely not, there are no conditions and the house is 100 per cent mine."
Life in a new build and advice for others
With a 10-year warranty covering her property, Cerys says routine maintenance issues aren't her concern, which "has been the most freeing thing". She noted: "The biggest thing going with a new build, yes the 5 per cent thing was very helpful, but not having to worry about rewiring the property or getting a new boiler. It's a big financial stress off my shoulders."
Her most important advice is to secure a reliable mortgage adviser. She explained: "If you have good solicitors and mortgage advisors to advocate for you when you feel you don't understand something it makes a huge difference." She added that getting on the property ladder is "more feasible" than many might think: "It doesn't matter your situation there are options and incentives out there, especially with new builds. Start by asking the question otherwise you might write it off without knowing."




