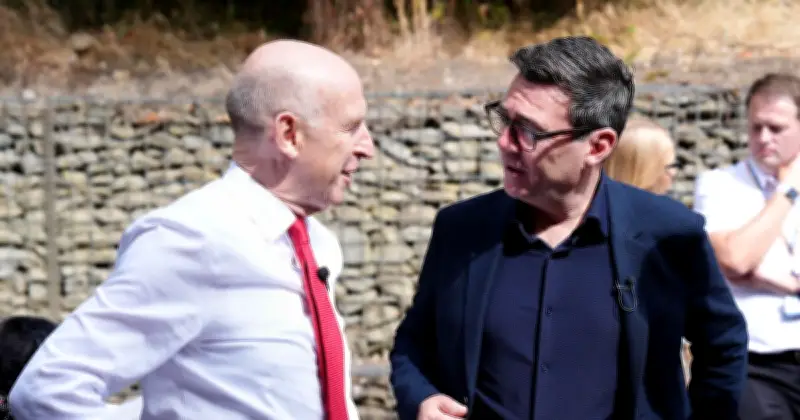
New Prime Minister Andy Burnham and Chancellor John Healey are preparing for their first Budget on October 28, with several tax rises either confirmed or under consideration. The announcement comes amid rapidly increasing borrowing costs and pressure from bond and gilt markets, which could squeeze the government's fiscal wiggle room.
Fiscal responsibility under pressure
Mr Burnham has stressed his administration's commitment to fiscal responsibility, stating that ministers are taking steps to reduce debt. He said: "We are taking the action needed to get debt down. This will be a Government grounded in fiscal responsibility. It will stick to the fiscal rules, but at the same time, we will help reduce cost-of-living pressure on our constituents, and that's the approach that we will take."
The markets are watching closely, as disbelief in the Chancellor's vision being properly costed and funded could send shockwaves through UK households, echoing the fallout from Liz Truss's mini-Budget.
Capital Gains Tax and property taxes
Capital Gains Tax (CGT) applies to profits on assets that have increased in value, including property (excluding primary residences) and stocks and shares. The first £3,000 of gains is tax-free, with rates of 18% or 24% depending on the taxpayer's income bracket. John Healey has already indicated he wants to bring CGT rates in line with income tax, which could see increases from 18% to 20% and from 24% to as high as 40%.
Property taxes are also under scrutiny, with Mr Burnham having previously criticised the council tax system's unfairness, noting that some small properties in Manchester pay more than mansions in London. A proportional property tax of 0.48% per annum is one option being floated, which would end the 'postcode lottery' of varying council charges.
Pension and state pension changes
As previously announced by predecessor Rachel Reeves, pensions will no longer be exempt from Inheritance Tax from April 2027. This means workplace pension values will be included in estate planning, potentially pushing estates over the £325,000 threshold (£500,000 including a main residence) that many previously avoided.
The state pension remains taxable, but an exemption has been announced for pensioners with no other income, which Mr Burnham will uphold. This is because the state pension is set to exceed the £12,570 tax-free Personal Allowance for the first time next April. However, those with additional income sources such as private pensions, property income, or other DWP benefits like Second State Pension (SERPs) will not be exempt, and tax paid will rise with the triple lock increase.