
The Reserve Bank of Australia lifted its key interest rate on Tuesday from 4.35% to 4.6%, its highest level since 2011 and the fourth increase this year, leaving many Australians reeling from the impact on their finances.
For a borrower with an average-sized new mortgage of $731,000 paying a typical rate of 6.2%, the rise would add about $119 to their $4,477 monthly repayments.
Families stretched to the limits
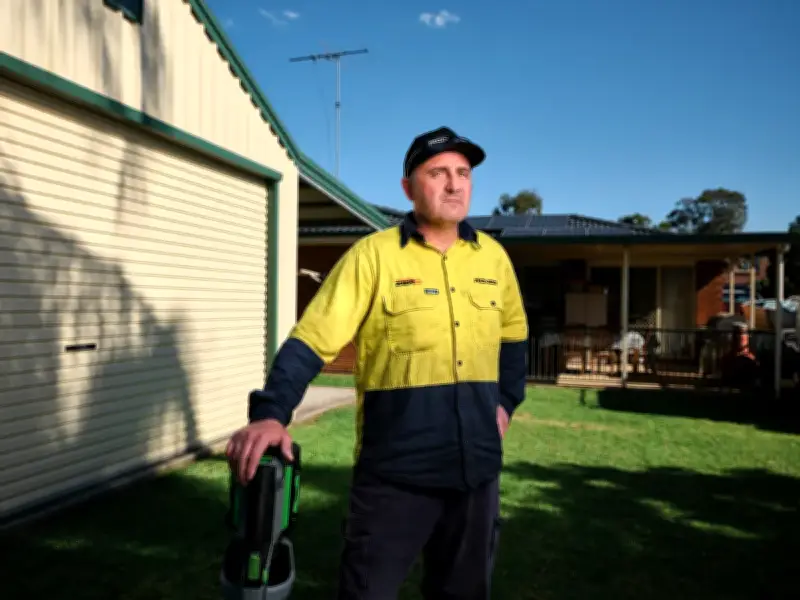
Shane McClymont, a 50-year-old toolmaker from Doonside in Sydney's west, said the hike was “daunting” for his family, whose finances are already “stretched to the limits”. He heard the news through a text from his wife, asking if they would be able to afford their son's birthday dinner this week.
“It's always special. The kids get to choose their takeaway of choice for their birthday,” he said. “She's wanting to know what we're going to do for dinner. We don't know if we can afford the takeaway or not, whether we're going to have to cook.”
McClymont bought his three-bedroom, one-bathroom home two decades ago and lives there with his wife and their four children, aged between 11 and 21. They still have a loan balance of $345,900, with McClymont paying $625 a week in repayments, including an additional $100 to help pay down the loan faster.
Cutting back on essentials
“We're going to have to cut back and it's going to be really tight … We've already cut all the streaming services, food, petrol, and we don't get to go away on family holidays or anything as much … if at all,” he said.
The family has also invested in a big freezer and now shops specials at wholesalers, Woolworths and Coles to make food last. McClymont said his wife, a stay-at-home mum, has had to go back into full-time employment.
He said he feels “robbed”. “It's just an endless cycle of the same thing. Every time you get a pay rise or something at work, it's taken off you tenfold with the increases in the bills. Every time you try and get ahead, you just keep going backwards.”
Anxiety over extra costs
Ann Mureithi, a 31-year-old freelance financial adviser and mother of two in Pakenham, Melbourne's south-east, is also worried by the hike. She moved to Australia from Kenya in 2018 as an international student, later met her husband, bought a home in 2023 and had two children – milestones that made her feel she'd achieved the “Australian dream”.
“When an increase happens, you're thinking, 'Where do I get that extra $200? Where do I get that extra $300?' That is such a scare because it's a lot of money. It's not like you have an option where you can say, 'oh, I'll cut this out',” she said.
The family pays more than 30% of their income towards the mortgage. Mureithi says the pressure has left her questioning whether she needs to work more, despite already struggling to find enough time while caring for two young children.
Further rises possible
Speaking after the announcement, RBA governor Michele Bullock said the board would raise rates again “if that's what's needed to get inflation down”, while acknowledging the impact on households and businesses.
“Now, I know this decision is difficult for households with a mortgage and businesses with loans, but high inflation hurts all Australians, especially the most vulnerable,” Bullock said. “Every household has seen how the price of everything has gone up in recent years. Pay packets don't go as far as they used to and that's why we need to stop this high inflation.”
But Mureithi says rising costs have left her feeling as though “there's a threat waiting for me”. “The anxiety, the small fear of: what if something happens? Then they get my house,” she said. “That is a scary part. That is where I don't feel like I'm still living the Australian dream.”




