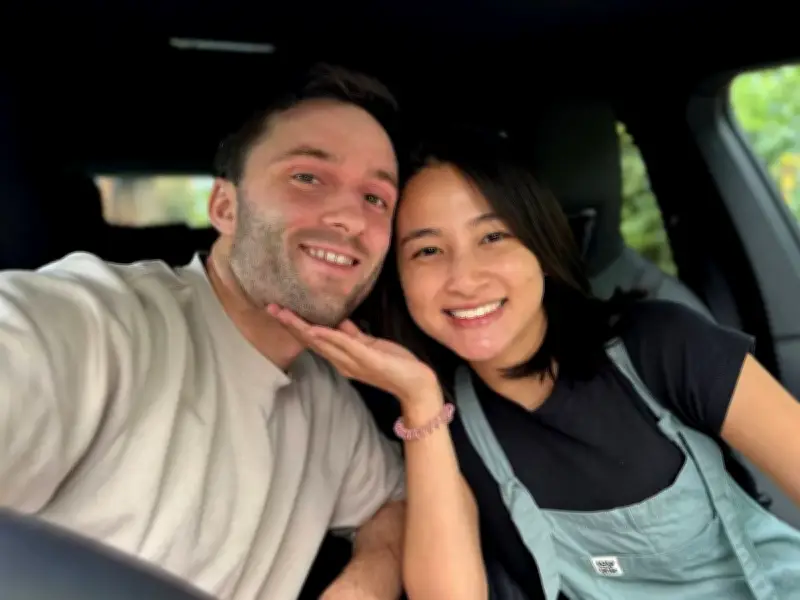
Bret Clay, 33, and Evey Clay, 32, from Telford, Shropshire, have a combined income of £239,000 but say they could not afford private school fees for their two children without strict financial planning. The couple, who have children aged two and five, live on Evey's £4,500 monthly salary as a doctor while investing Bret's income from his work as a financial content creator.
Living on one salary to fund education
The family gets by on Evey's monthly wage, which amounts to £89,000 a year, to cover their mortgage, household bills and other outgoings. Bret's earnings from content creation, forecast at £150,000 this year, go directly into stocks and shares ISAs with Trading 212 and Vanguard.
Bret's monthly income ranges from £2,000 to £10,000, and all of it is deposited into an investment account. The couple have accumulated £600,000 in investments, including £200,000 in returns, and estimate they will hold over £1 million in investments by the time their children reach private school age.
Planning for rising fees and VAT
The couple intend to send their children to private school at age 14, rather than earlier, to balance saving for education with supporting them through university. Bret said: "Without investing and proactively planning, I don't think our earnings would be enough to send two kids to private school."
He added: "Private school costs are expected to rise, and could be £40,000 each a year, by the time our kids get there, and there's the added cost of VAT these days. We're choosing to send them when they are 14, so we have extra money built up and we want to make sure we have enough money to be able to help them through university as well."
Local private school fees currently stand at approximately £25,000 annually, though the couple anticipate this could rise to £40,000 by the time their children reach school age. They considered private primary school or starting in year 7 but settled on waiting until age 14.
Strict spending habits and savings strategy
After having children, the couple began depositing £250 monthly into each child's junior stocks and shares ISA. Since children cannot access these funds until age 18, they use their own investments to build up money for educational expenses.
The couple follow "intentional spending" principles, avoiding subscriptions like Netflix, ordering only tap water when dining out, and never ordering takeaways. They have kept the same car for 10 years and bulk buy items such as toilet paper and meats from Costco.
They also hold £40,000 in an emergency fund, rotating which bank holds it every three months to secure the most competitive interest rate. Their savings currently sit in a Monzo saver account offering a 3.8% interest rate.
Bret said: "We make it a habit to save as much as we can, instead of wasting money. We also don't go crazy on each other's birthdays, or special occasions, and get each other something small and thoughtful, instead of something expensive."
Should the couple's earnings increase in the future, they would consider bringing forward the age at which their children enter private education.