
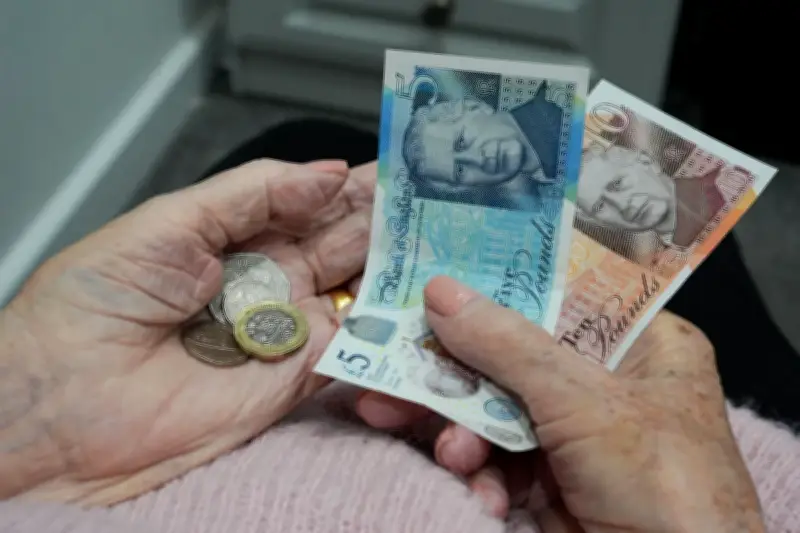
The triple lock policy used to increase state pensions has come under the spotlight amid speculation over how potential reforms to social care in England would be funded.
While any changes would not come before the next general election, ministers have refused to confirm whether Labour’s commitment to the triple lock will be in the next manifesto, fuelling speculation that an eventual move to a less generous system could be on the cards.
What is the triple lock?
State pension increases which take place in the month of April are based on the triple lock policy. Under the triple lock guarantee, the state pension increases in line with whichever is the highest out of three figures.
These are total earnings growth in the year from May to July of the previous year, CPI (Consumer Prices Index) inflation in September of the previous year, or 2.5%.
How do pensioners benefit?
The policy helps increases in pensioners’ incomes keep pace with the working population and living costs. The cost-of-living squeeze, with rising bills, has hit many households in recent years and many pensioners live on fixed incomes which may give little wriggle room in their budgets.
The state pension can be a particularly vital cushion for pensioners living on lower incomes. According to a report from wealth manager Quilter, for retirees aged 65 to 79 with below-average retirement incomes of £25,000 or less, the state pension provides 57% of retirement income, while for those aged over 80 with below-average retirement incomes it accounts for 54%. The state pension accounts for nearly a quarter (24%) of income across all retirees, the analysis indicated.
Why has it been controversial?
In general, the triple lock policy has been part of a wider debate around generational fairness and cost burdens faced by younger generations.
People relying solely on the full new state pension currently look on course to breach the personal tax allowance next year, as recent Office for National Statistics (ONS) figures showed total wage growth, including bonuses, stood at 3.9% in the quarter to July. While still to be confirmed, and not all the pieces of the triple lock puzzle yet in place, this implies the full new state pension could top £13,000 next year. The personal tax allowance has been frozen at £12,570 since 2021.
However, many pensioners do not receive the full state pension. The Government has previously said pensioners who are wholly dependent on the new state pension, with no private pension, or the old basic pension, with no increments, will not have to pay tax. Further detail is expected to be set out in the Budget.
What is the cost of the state pension?
The Institute for Fiscal Studies (IFS) has previously said that public spending on the state pension in 2026–27 is expected to be around £154 billion and that the triple lock has increased annual spending on the state pension by around £16 billion, compared with uprating in line with average earnings growth since 2010.
Recent comments on the triple lock
Baroness Altmann, a former pensions minister, recently said there should be a cross party review “to decide how best to uprate state pensions without political point scoring”. The leader of trade union Unite said reforming the pensions triple lock to fund social care would be “morally wrong”.
Sharon Graham told BBC Radio 4’s Today programme: “Instead of going and trying to pick the pocket of pensioners, we need to move over to the other side of the equation and look at things like wealth taxes, way before we try to stop something like the triple lock.”
What about future pensioners?
Today’s working age population are tomorrow’s pensioners – and concerns have been raised in recent years that many are heading for a retirement income shortfall – potentially making some even more reliant on the state pension. In May, the Pensions Commission said around 15 million people are thought to be under-saving for their retirement.
Women, low and middle earners, and the self-employed are among those who could be particularly at risk, according to the commission, which warned the number of people under-saving for later life could reach 19 million without action.
Defined benefit (DB) pensions that guarantee an income in retirement have become more thin on the ground and while millions of people have been brought into workplace pension saving through automatic enrolment, many are not thought to be saving enough. Some groups of people, such as the self-employed, are not included in auto-enrolment.




