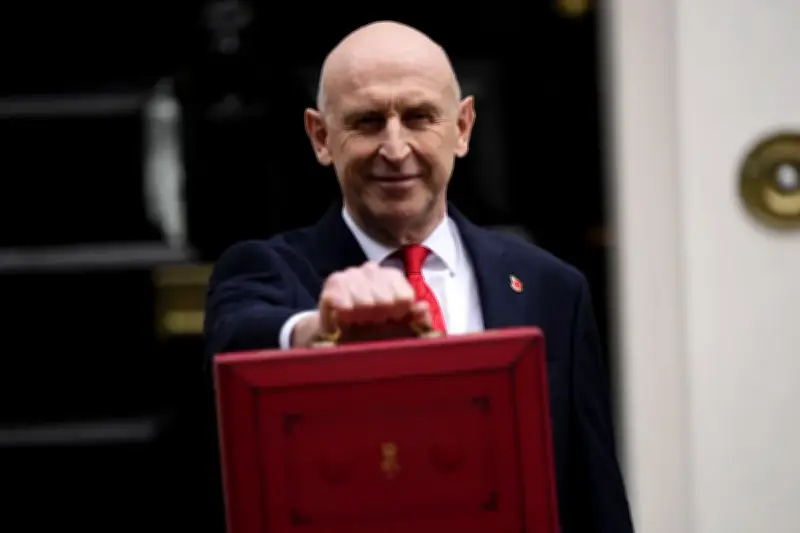
Record debt interest costs drove UK government borrowing to £17 billion last month, according to the Office for National Statistics (ONS), highlighting the pressure on Chancellor John Healey to keep public finances on track.
Debt interest costs rose by £11.2 billion in October, the highest figure for that month on record and £2.8 billion more than a year earlier. The ONS said this was only the ninth time monthly debt interest has exceeded £10 billion since records began in 1997.
Borrowing rises despite lower-than-expected total
The higher debt costs helped push public sector net borrowing up by £800 million, or 5.2%, year on year. However, overall borrowing was marginally lower than the £18 billion that most economists had forecast.
In his inaugural budget last month, Mr Healey said he would cut the UK's fiscal headroom to £15 billion in 2029-30, down from a previous prediction of £26 billion, after a jump in borrowing costs. The weaker headroom, which is expected to improve to £22 billion by 2031, was linked to a £14 billion rise in debt interest costs over the past year.
Year-to-date borrowing remains third highest on record
In the financial year so far, government debt stood at £111.3 billion, £7.3 billion or 6.1% lower than the same period a year ago, keeping the government on track to reduce the deficit in the 12 months to March 31. This was helped by a £3.6 billion downward revision to previous monthly data, though year-to-date borrowing was still the third highest on record, behind 2020 and 2024, the ONS said.
ONS chief economist Grant Fitzner said: “Borrowing so far this financial year remained lower than in the same period last year with receipts growing faster than spending. Income-related taxes’ receipts grew particularly strongly. However, monthly borrowing was up on last October, partly due to higher debt interest.”
Debt levels and fiscal outlook
The government's total debt stood at £3.1 trillion last month, having passed £3 trillion for the first time in September, or 95.8% of gross domestic product (GDP), up from 93.9% a year ago.
At the October budget, the Office for Budget Responsibility predicted rising national debt levels compared with the size of the economy over the next three years amid higher-than-expected state borrowing. The OBR said borrowing is expected to surpass previous forecasts by around £18 billion this year, £16 billion in 2027/28, and an average of £11 billion a year after that.
Chief Secretary to the Treasury Emma Reynolds said: “This year we’ve cut borrowing faster than any other G20 country. Now we’re going to cut waste and bureaucracy by reprioritising spending and making public services more efficient with AI.”
Rob Wood at Pantheon Macroeconomics said the latest public finances data “brought some good news for the Chancellor, with borrowing for October likely running below expectations made in the Budget”. But he added: “The October Budget did little to address the more serious challenges facing the public finances, so we continue to have doubts about the Government’s ability to follow through on its fiscal plans, suggesting upside risks to borrowing in the coming years.”