The Department for Work and Pensions (DWP) has revealed that 115,321 people made voluntary National Insurance payments after checking their State Pension forecast online, as it urges others to use the government tool.
Newly published Parliamentary data shows that approximately 18 million people used the State Pension forecast tool over the past two and a half years. Of those, around 170,000 found gaps in their National Insurance record.
Of that group, 115,321 went on to make voluntary payments in an attempt to fill those gaps, according to the figures.
Minister's update on voluntary contributions
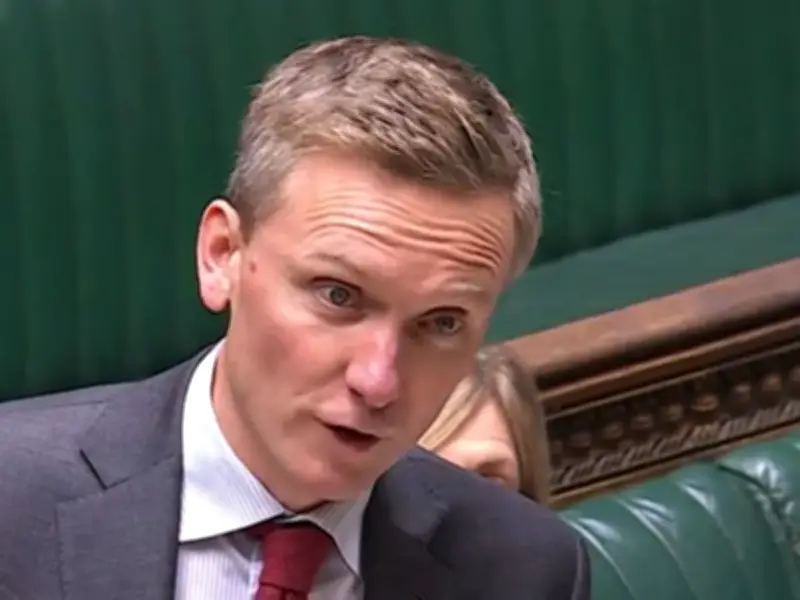
The issue came under the spotlight this week after DWP and Treasury minister Torsten Bell provided new details following questions about whether there was an estimate of how many people could boost their State Pension entitlement by making voluntary National Insurance contributions.
Bell, Parliamentary Secretary at Treasury, which represents HMRC in Parliament, said: "NI contributions and credits can be built up throughout a person's working life. Their State Pension entitlement will therefore depend on their contribution history, credited years and any future qualifying years they may accrue before reaching State Pension age."
He added: "HMRC cannot forecast an individual's future income or NI contributions to determine whether they could increase their State Pension by making voluntary contributions. HMRC holds information on customers who made voluntary NI contributions online after checking their State Pension forecast online."
The minister explained the figures: "These figures relate only to customers who paid voluntary NI contributions online after checking their forecast through the online Check your State Pension forecast service. They do not include customers who checked their forecast and then paid outside the service, or customers who obtained a forecast through DWP and then paid outside the online service."
Bell also noted that HMRC encourages customers who are able to do so to check their State Pension forecast online or through the HMRC app. Customers who cannot use the online service can contact the DWP Future Pension Centre to request a forecast.
Rules on NI contributions and Martin Lewis's advice
In Britain, you must have at least 10 qualifying years on your National Insurance (NI) record to receive any new State Pension. To claim the full amount, you need approximately 35 years.
A qualifying year can be secured by working and paying National Insurance contributions, or through receiving National Insurance credits - for example, if you were unemployed, ill, or a parent or carer. You might also qualify if you have lived or worked abroad, or paid a reduced rate of National Insurance as a married woman.
Martin Lewis spoke recently on his podcast about NI contributions. He was asked by a woman who was considering paying to cover two years to increase her total qualifying years to 10. She had been working overseas for several years and had also spent some time in education.
She asked: "I am currently 36. Is it worth paying the two now or would it be considered a waste of money as I am likely to reach the 35 years needed for a full state pension anyway?"
Mr Lewis told her to check the forecast, saying: "The first thing I'd do is I'd go and look at your pension projection. On your pension projection, your state pension projection, which is on gov.uk, are you predicted to be able to get that you will have the full state pension when you retire, which is a very long time away?"
He added: "If you are, I think this is probably overkill, because it's not like once you get to the full state pension, you earn more NI years, you get even bigger than the full state pension. It doesn't work like that."
He then noted: "The only time I would make an exception on that is if you could buy these years really, really cheaply. If any of these are part years - so a part year is where you have almost got all the contributions you need to get a year but you are not quite and it's binary. I know people who have been able to buy a part year for £15."
He continued: "Normally it's going to cost you, a full year, in the 900ish pounds. But if you could buy a part year for 15, 20, hey maybe 50 quid, even at your age, just in case something happens in future, as you can only buy back a certain amount - 6 years - I'd be tempted to go, you know what, it's 50 quid, I'm just going to do it, just on the off-chance that I might need it at some point in the future."
Why gaps occur and how to fill them
The government's dedicated webpage on the subject says gaps in your National Insurance record could be down to receiving National Insurance credits for less than a complete tax year, or being self-employed without making contributions due to limited profits. Further reasons may include living or working overseas, being in low-paid work, or being out of employment without claiming benefits.
If you have gaps, it is advisable to check whether you qualify for National Insurance credits before choosing to pay voluntary contributions. There are specific circumstances in which voluntary contributions cannot be made.
This may be relevant if you are a married woman or widow paying a reduced rate of National Insurance. It may also apply if you have missed the deadline for paying contributions for periods containing gaps. Additionally, it could be relevant if you have no gaps in your National Insurance record - unless you are receiving Class 3 credits and are eligible to pay Class 2 contributions.
Contact HM Revenue and Customs (HMRC) if you think your National Insurance record contains an error. However, bear in mind that voluntary contributions do not always increase your State Pension. This might be the case, for instance, if you were contracted out.
If you are below State Pension age, check your State Pension forecast to determine whether you would benefit from paying voluntary contributions. You can also reach out to the Pension Service. If you have reached State Pension age, contact the Pension Service to find out whether voluntary contributions would be of benefit. If you are living or working abroad and you are over, or within 6 months of reaching State Pension age, contact the International Pension Centre for guidance.