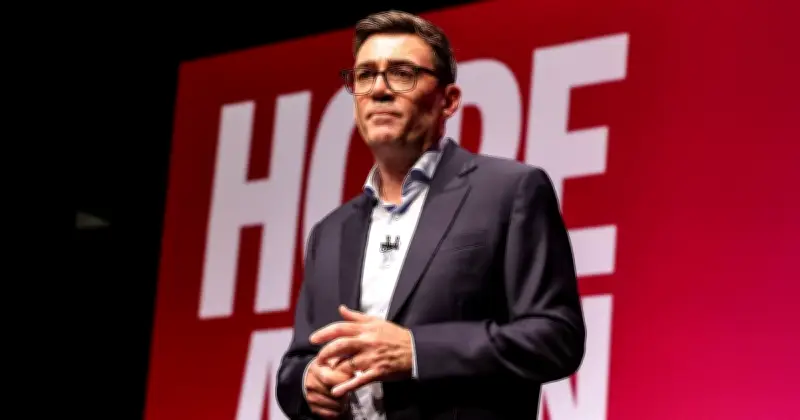
Prime Minister Andy Burnham has announced that the Triple Lock for the State Pension will be adjusted after April 2030. The change was revealed during his speech at Labour's party conference yesterday, where he said the tweak would fund a National Care Service free at the point of use, similar to the NHS.
“We promised in our manifesto to keep the Triple Lock unchanged throughout this Parliament,” he said. “I will honour that promise. I will honour that promise, and I will do more. That promise will take the state pension to a record high. From there, in April 2030, we will adjust it.”
What the change means for pensioners
The State Pension will continue to increase every year at least by prices or 2.5%, Mr Burnham said, and will “hold its value relative to earnings over time”. Under the change, the annual link to earnings would be dropped, meaning the State Pension would rise each year by the higher of inflation or 2.5%.
“Some may not realise it but older people with nothing more than the State Pension, or only a little more, can find themselves paying care charges today from that small income,” he added. “Under my plan, this will no longer happen.”
Reaction and expert advice
Andrew Prosser, head of investments at InvestEngine, said: “The Prime Minister's proposal to keep the Triple Lock throughout this Parliament, but adjust it from April 2030 to help fund a national care service, is likely to be one of the most divisive announcements to come out of Labour conference, with some in his party already calling it 'electoral insanity'.”
“The detail of the changes is still to be seen, but it is important to remember that while the triple lock has historically made the State Pension more generous, it is still rarely enough to fund the retirement most people picture. Moving to a 'double lock' could leave a larger gap between what retirees receive from the state and what they actually need.”
“While reform may help address long-term pressures from an ageing population and rising pension costs, it would also reinforce the importance of building private retirement savings alongside the State Pension.”
Mr Prosser then advised Brits to make full use of employer pension contributions and the tax advantages available through workplace pensions, SIPPs and ISAs, where possible.