Firmus Technologies is on track to launch the second-largest IPO in Australian history, but community backlash in Tasmania and investor skepticism over its valuation are casting a shadow over the multibillion-dollar float.
The Australian company, which develops AI datacentres, is preparing to list on the ASX later this month after an anticipated initial public offering designed to raise $7bn from investors. It is on track to be the second-largest IPO on record behind Telstra's $14bn share sale in 1997, and one of the top five in the world this year.
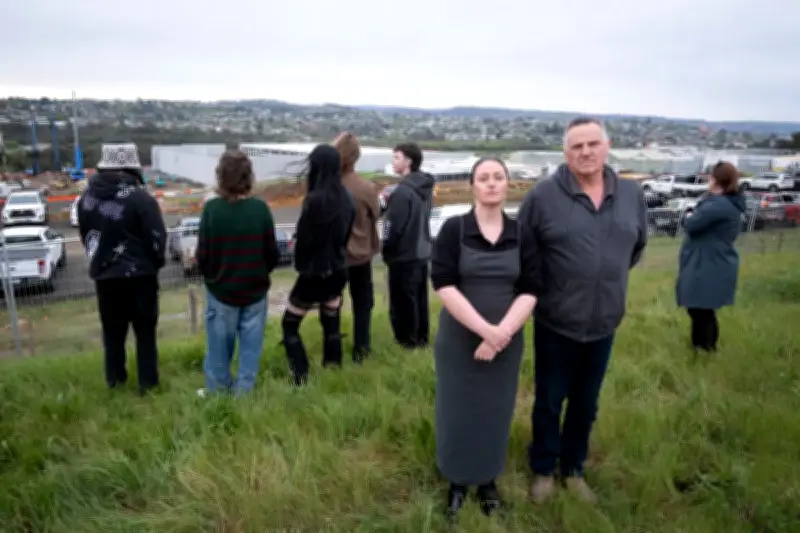
From her balcony in Launceston, Kayla Thompson can see the buzz of construction at what will soon be one of Australia's first AI factories. Her teenage stepchildren get an even clearer view from their classroom window. Like many of her neighbours, Thompson didn't realise Firmus had an ambitious plan to build datacentres in Tasmania until after construction began.
Community backlash over approval process
Its massive 104-megawatt datacentre at St Leonards, worth an estimated $2.1bn, was given fast-tracked approval by the city of Launceston in September last year without a public hearing. Thompson was furious and joined a protest group that believes Tasmanians were kept in the dark by the company.
"Their consultation was nonexistent until they had it shoved in their face that they made a mistake," says Thompson. "By then, it was too late. The more we researched this company, the less appropriate it seemed that size of facility should be voted on by a local council with limited community awareness."
In June, Firmus realised it had a problem. Community backlash was threatening two other proposed datacentres in the state's north-east. With an IPO months away, it organised dozens of public consultation sessions with a pre-prepared message.
"They did a bit of a mea culpa and said we handled that badly and we should have done something more," says Joe Zadravec, who lives close to another proposed Firmus datacentre. "But they only did that after they were caught."
A Firmus spokesperson confirms the company overhauled its community engagement program after receiving strong feedback from Launceston locals. "The feedback we receive will continue to help shape our approach," they say.
Soaring valuation questioned
As Firmus prepares to ask prospective shareholders for billions of dollars in the heat of a global AI boom, its Tasmanian missteps offer an unfiltered look at the operational risks behind the pitch. A year ago, as local councillors approved the five-hectare AI factory in Launceston, Firmus was worth just under $2bn in a private funding round.
As plans emerged to build liquid-cooled datacentres across the Asia-Pacific alongside AI chip maker Nvidia, which acts as both an investor and hardware supplier, that valuation surged. In less than 12 months, the implied valuation leaped from $2bn toward a targeted $40bn-plus ASX debut. Now, investment analysts are dangling figures as high as $100bn, a price tag that would make Firmus twice the size of Telstra.
One investment manager who viewed the company's draft prospectus tells Guardian Australia the valuation "keeps randomly compounding when nothing has really changed". "I'm not saying it's not worth anything, it's just not worth the valuation they're trying to get it away at," the investment manager says.
The majority of its ambitious pipeline is unbuilt, with the company now operating just two facilities, one in Melbourne and the other in Singapore. The draft prospectus shows Firmus is forecasting $5bn in annual earnings once its development pipeline progresses, which would put it in the top tier of ASX earners.
"This is a capital-hungry business that needs to keep raising debt and/or equity to fund the losses, and meanwhile we're being told this will have $5bn of earnings within a few years – it's a little bit of a fairytale," the investment manager says.
A Firmus spokesperson declined to comment when asked a series of questions by Guardian Australia regarding the feasibility of its earnings forecast and valuation.
Industry-wide obstacles
While Firmus relies on the prompt construction of datacentres to justify its valuation, the US, which is further along in the AI datacentre boom, offers a sobering look at the obstacles ahead. A comparable datacentre offering was recently delayed in the US after bankers struggled to find buyers willing to support a sought-after valuation of US$50bn or more, the New York Times reports.
Part of the problem is that datacentres are hitting community resistance, with US cities Tulsa, New Orleans and Birmingham among those implementing temporary bans on permits and construction. In Sydney, infrastructure company Goodman Group has just withdrawn its plans for a datacentre near a public school amid fierce local opposition, in a clear warning to the industry they must win over local communities.
Community anger typically stems from the scale of the datacentres, their strain on power grids and water supplies, heavy use of diesel backup generators, and the speed of approvals that have left residents feeling shut out.
Retail investor risks
Rob Talevski, the chief executive of Webull Securities Australia, says there's a danger retail investors become the "exit strategy" for Firmus's institutional investors. New York trading houses Blackstone and Jane Street are among the early backers who may look to the public float to offload their stakes at high prices.
Firmus is offering what is known as a small free float, whereby the company's founders and early investors initially retain most of the company's shares. This can create a temporary scarcity of stock that initially drives the share price higher, giving those backers the ability to offload their holdings at inflated prices before their stock floods the market.
"The question retail might have to ask is, are they basically the liquidity exit strategy for some of the early investors?" says Talevski. "That's the bit that probably is not spoken about enough, and that's where the question marks are for a retail investor."
There are no escrow arrangements in place for major backers like Blackstone, leaving institutional investors free to sell down their stakes immediately after it lists. The founders – Oliver Curtis, who has spent time in prison for insider trading, his cousin Tim Rosenfield, and Curtis's former brother-in-law Jonathan Levee – can begin selling some of their holdings as early as six months after listing if the stock price rallies.
Richard Hemming, the editor at Under The Radar Report, says there are so many interested parties pushing for a successful IPO, including brokers, investment banks and early institutional investors, that the risks to retail investors have been understated. "Telstra is one of the biggest companies in Australia and these guys are just coming from nothing and saying that they're going to be bigger than Telstra – it's gobsmacking," says Hemming.
Back in Tasmania, Firmus has turned to a tested method of countering bad press: sponsoring major sporting teams. The company's name will now be carried by the Tasmanian Devils AFL team, Cricket Tasmania, and the JackJumpers and Jewels basketball teams, in what Emma Sherry, the dean of RMIT's school of management, says is a classic case of "sportswashing".
"This works until it doesn't. The goodwill relies on a bet that the community loves the sport enough to forgive the potentially problematic relationship," she says. Firmus believes that's unfair. They say the company was founded in Tasmania, which is home to its staff who are passionate about sport. "Our sporting partnerships are not a substitute for genuine and thoughtful community engagement," the spokesperson says.
So far, the deals have done little to ease concerns of vocal critics. "We are already distrusting of AI in a general sense," Thompson says. "Why would we trust this company?"